
A buyer came to us for an SBA business plan on a $3M construction company. A lender with sharper pricing moved his SBA 7(a) rate from Prime + 2.25% to Prime + 1%: about $232K less interest.
A buyer reached out to us about an established construction company he was under contract to buy for about $3 million. He'd already picked his lender. It was a bank he had a relationship with, and they'd approved him. They had asked for an SBA business plan, and that's all he hired us for.
He was putting 10% down on a 90% SBA 7(a) loan, with no seller note. The rate he'd been quoted was Prime + 2.25%.
The rate he'd been quoted was higher than what I thought my lender would offer. The more I asked about his deal and looked at the business's financials, the more I thought this was a really strong deal, and I was pretty sure he could get a better rate.
The hard part was that he didn't really want to switch. He liked having a local lender connection, and his bank already held his home mortgage. He was skeptical in general, about me and about working with a different lender, and I understand why. He reached out for help with a business plan, and next thing you know I'm trying to get him to switch lenders. He didn't really understand why one bank's rate would be so much lower than another's on the same SBA deal.
There was a second problem I didn't see coming. His bank told him they couldn't confirm an interest rate until the very end of the process. He'd have to go through underwriting, and put in all that time and effort, before he knew what rate he was getting.
We ran our SBA Pre-Qualification first. The business had grown steadily for three years, and on its most recent year's numbers it covered the proposed debt payments about 2.7 times over.
Then we built the projections, with the business's seasonality built in, and wrote the business plan. The plan had one main job. The buyer lived about two hours from the business, and the lender wanted a good operating plan for that distance. A lot of what we convinced the lender of was that the current owner wasn't there every day either. The crews are out at job sites, and some of those sites are closer to the buyer's home than the office is. The plan showed him at the office a couple of days a week and at job sites the rest. It also showed him growing sales near where he lives, so the business would naturally move closer to him over time.
I brought the deal to one national SBA lender that keeps its loans on its own balance sheet instead of selling them on the secondary market. That's where their flexibility on rate comes from: they aren't pricing the loan to sell it. Explaining that helped the buyer understand why the rate could be lower at one bank than another.
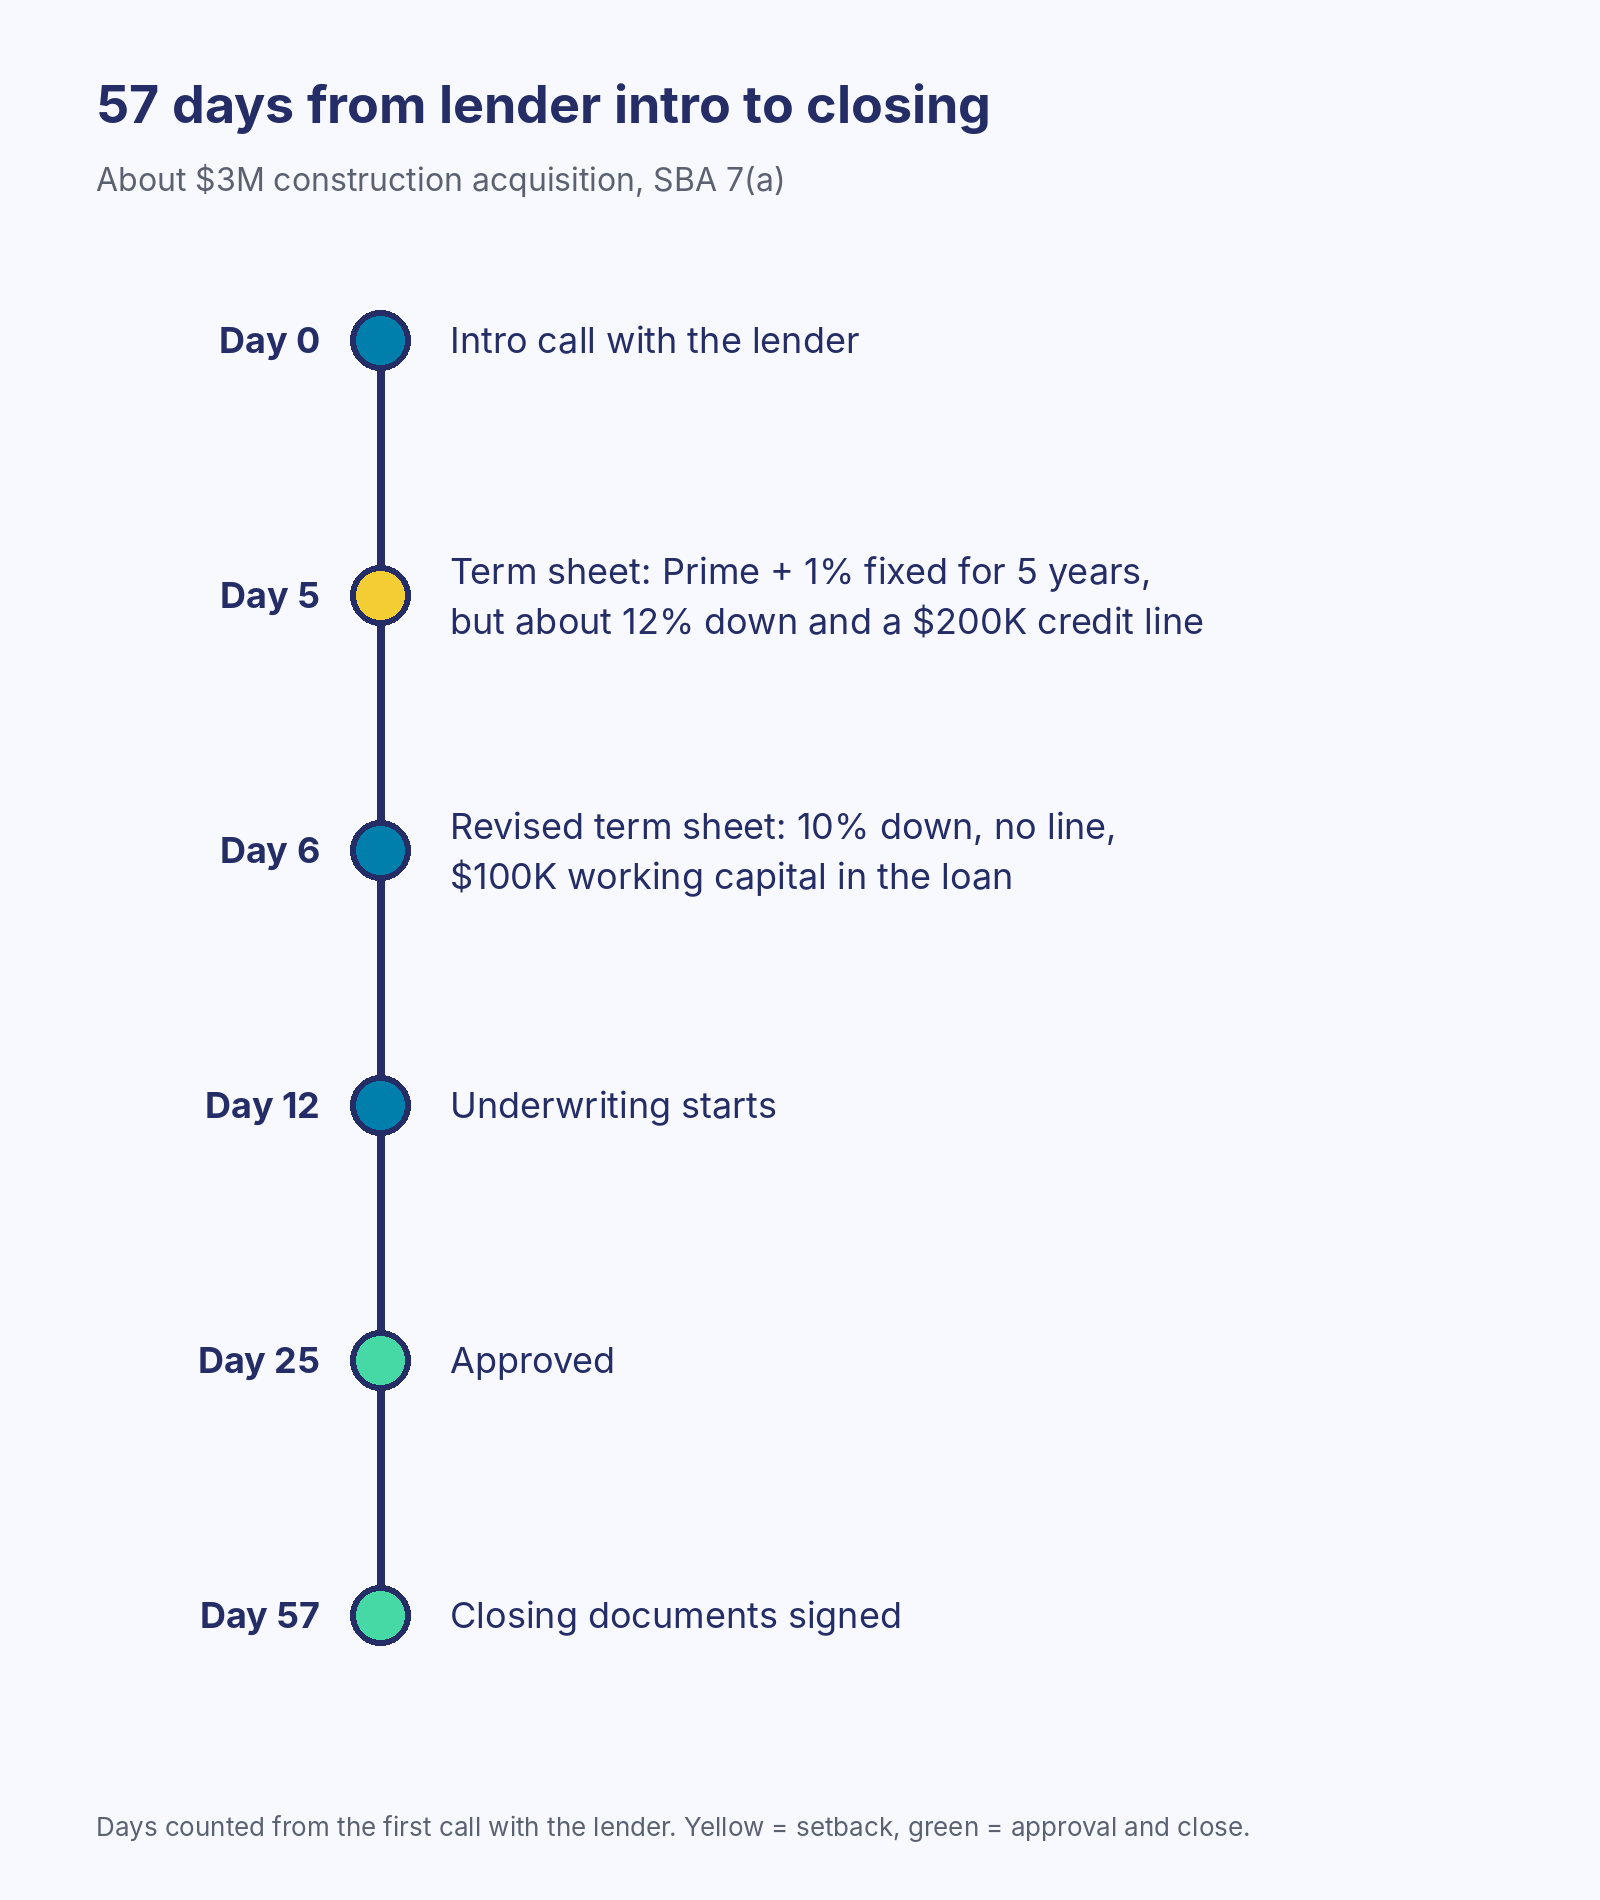
Five days after our intro call, the lender issued a term sheet, with the rate written right on it: Prime + 1% fixed for five years, about 7.75% at the time. But the first version capped the bank at $3 million total. That meant a smaller term loan plus a $200,000 line of credit, and the buyer's equity went up to about 12%. He didn't want to put in the extra money, and he was pretty sure he didn't need the line.
He pushed back on the lender and asked for more. His own savings after closing were what made the lender comfortable. That same evening, a revised term sheet came back: a loan of about $3 million, 10% down, no line of credit, and $100,000 of working capital built into the loan.
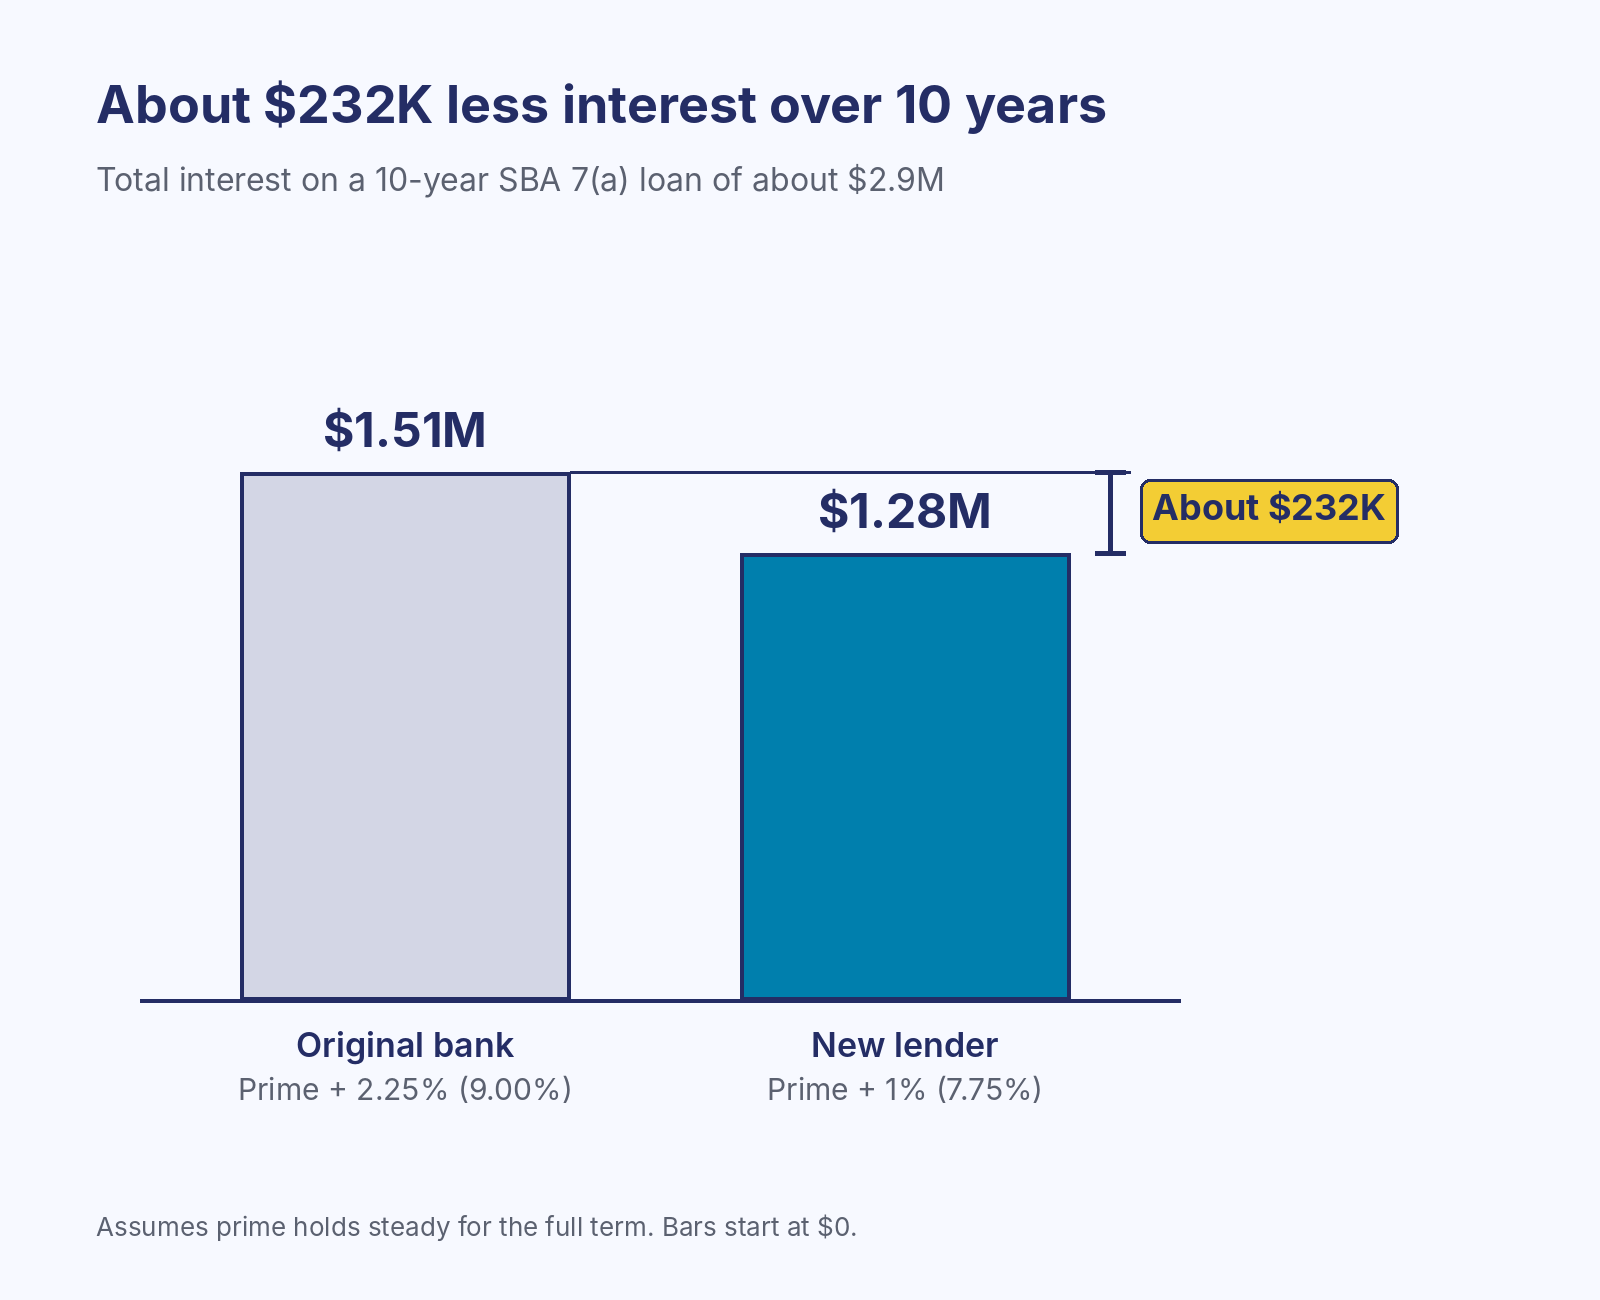
The deal went into underwriting about a week later, got approved 13 days after that, and closing documents were signed 57 days after our first call with the lender. The buyer got Prime + 1% fixed for five years, compared with Prime + 2.25% at his original bank, which was 1.25 points lower. Assuming prime stays where it was, that comes to about $232,000 less interest over the 10-year loan.
It really was kind of a dream deal. Most deals seem to have to die a couple of times along the way, and this one didn't. A few things made that possible. The buyer is an engineer and just an organized person. The seller was easy to work with and offered a really fair price. That was probably the most surprising thing. I think he could have sold the business for $500,000 to $1 million more, but he'd made his money, liked the buyer, and wanted to see him move the business forward. Buyer and seller were also already far along when they came to us. The purchase agreement was drafted and agreed by both sides and their lawyers, so there was none of the legal back-and-forth that usually comes after an LOI, and that's where deals often get delayed or die.
Have questions about your own deal?
Already have a rate quote? Send us your deal and we'll tell you for free whether you're leaving money on the table.

Adam will review your deal before you talk to lenders and tell you honestly what lenders will flag. No cost.
Get a free SBA review