
A retiree starting a dump truck hauling company got about $850K in SBA 7(a) financing for three new trucks. A mission lender approved it 5-0 after a key-employee credit problem.
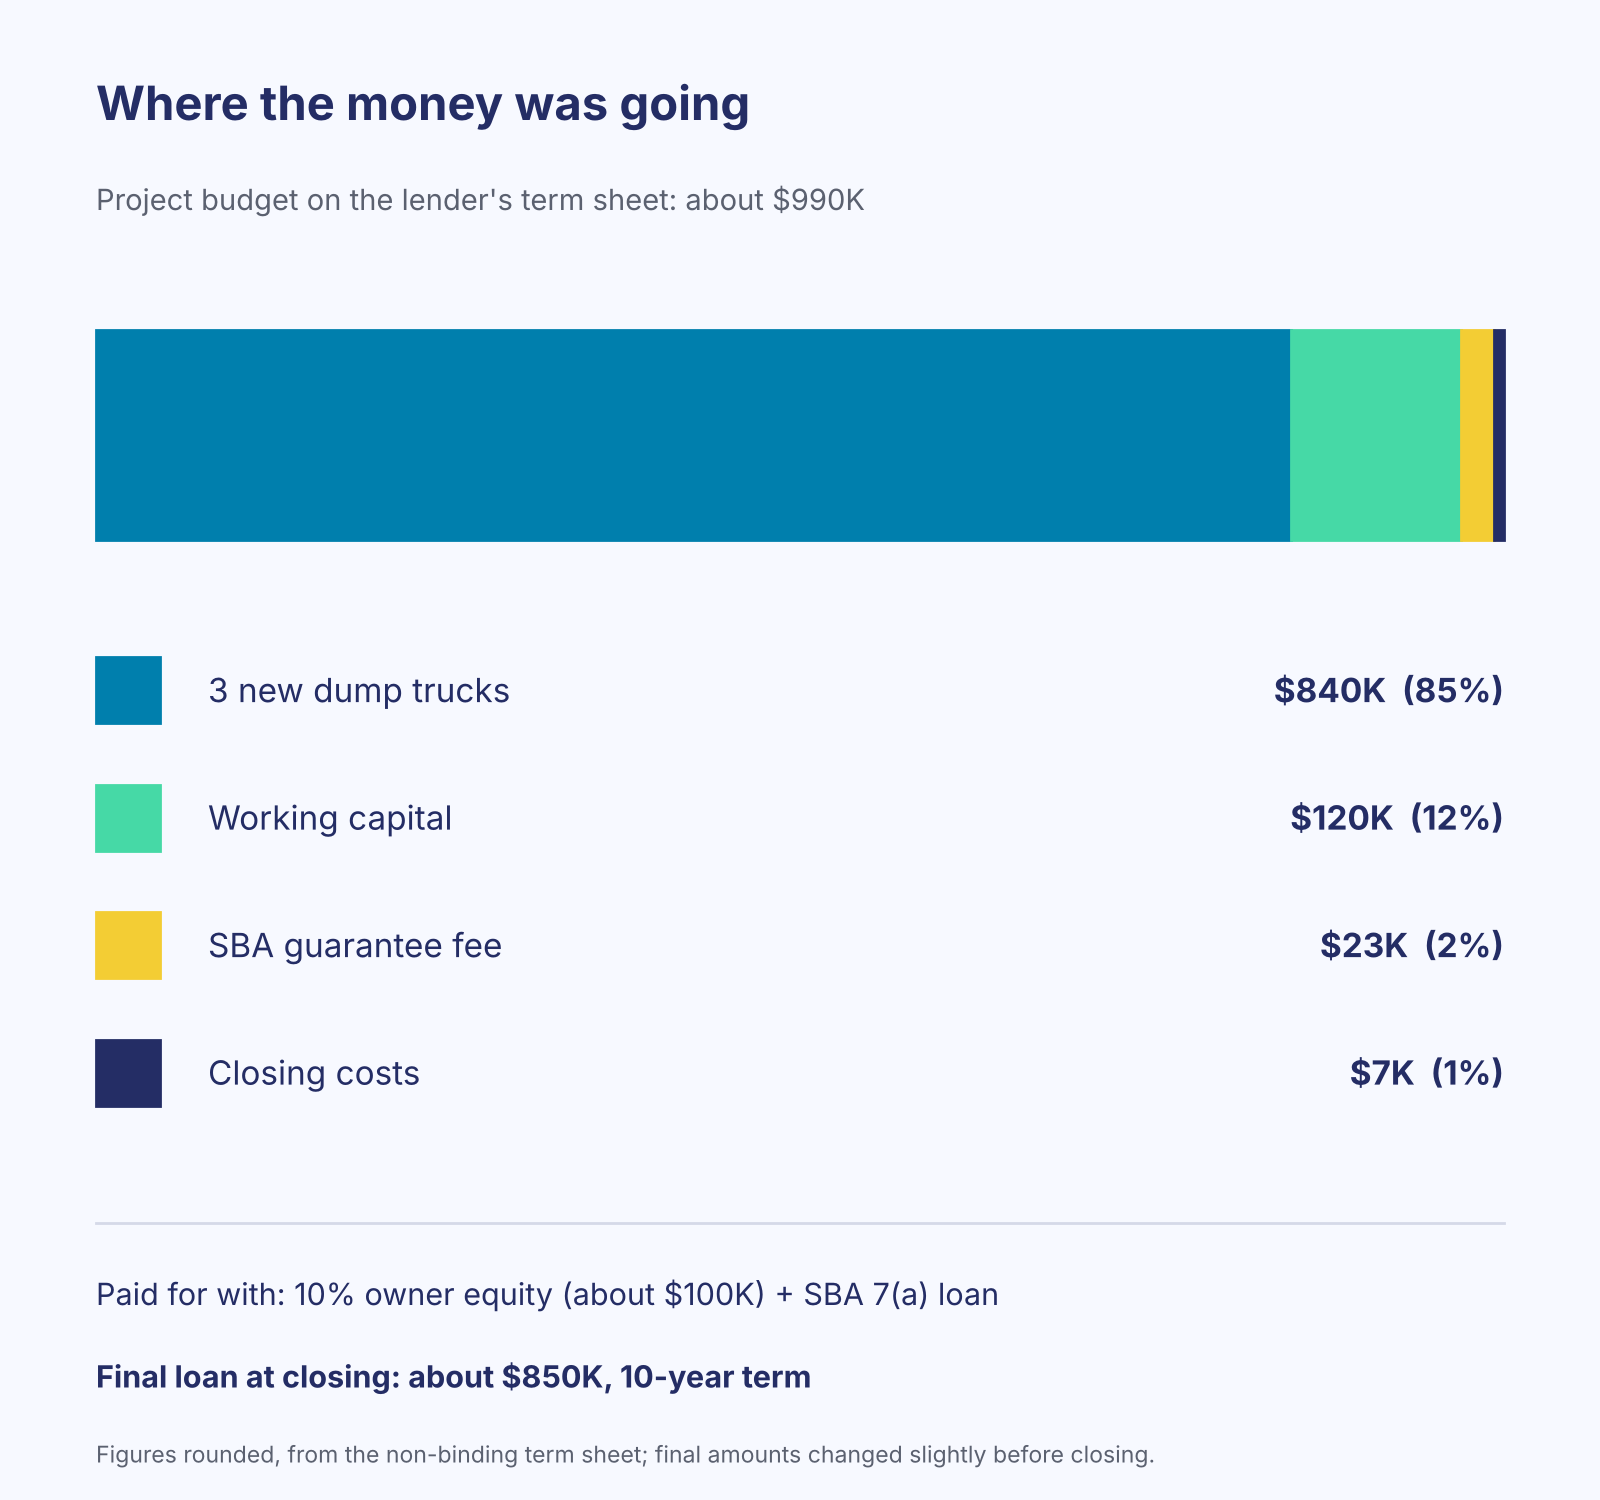
A first-time business owner came to us wanting to start a dump truck hauling company in a fast-growing metro area in the Southeast. He had just retired from a long career running transportation operations in local government, and he wanted to start with three brand-new trucks at about $265K each. All in, the request was close to a million dollars, with 10% down.
Honestly, I wasn't sure I'd be able to find a lender to get on board. A startup trucking business is one of the toughest deals to get a lender to agree to. The collateral is what's called rolling stock. You can't repossess a truck the way you can a building, and if the borrower defaults, those trucks could be anywhere in the country.
Then there was the size. Most lenders would tell a startup to buy one truck and see how it goes, not three before the first sale. But his logic made sense to me. He wasn't planning to drive. For the business to pay the drivers, cover operating costs and still pay him a reasonable wage as the manager, it needed a certain scale. One truck just wouldn't make enough. He was looking at it from a financial math perspective, which I liked.
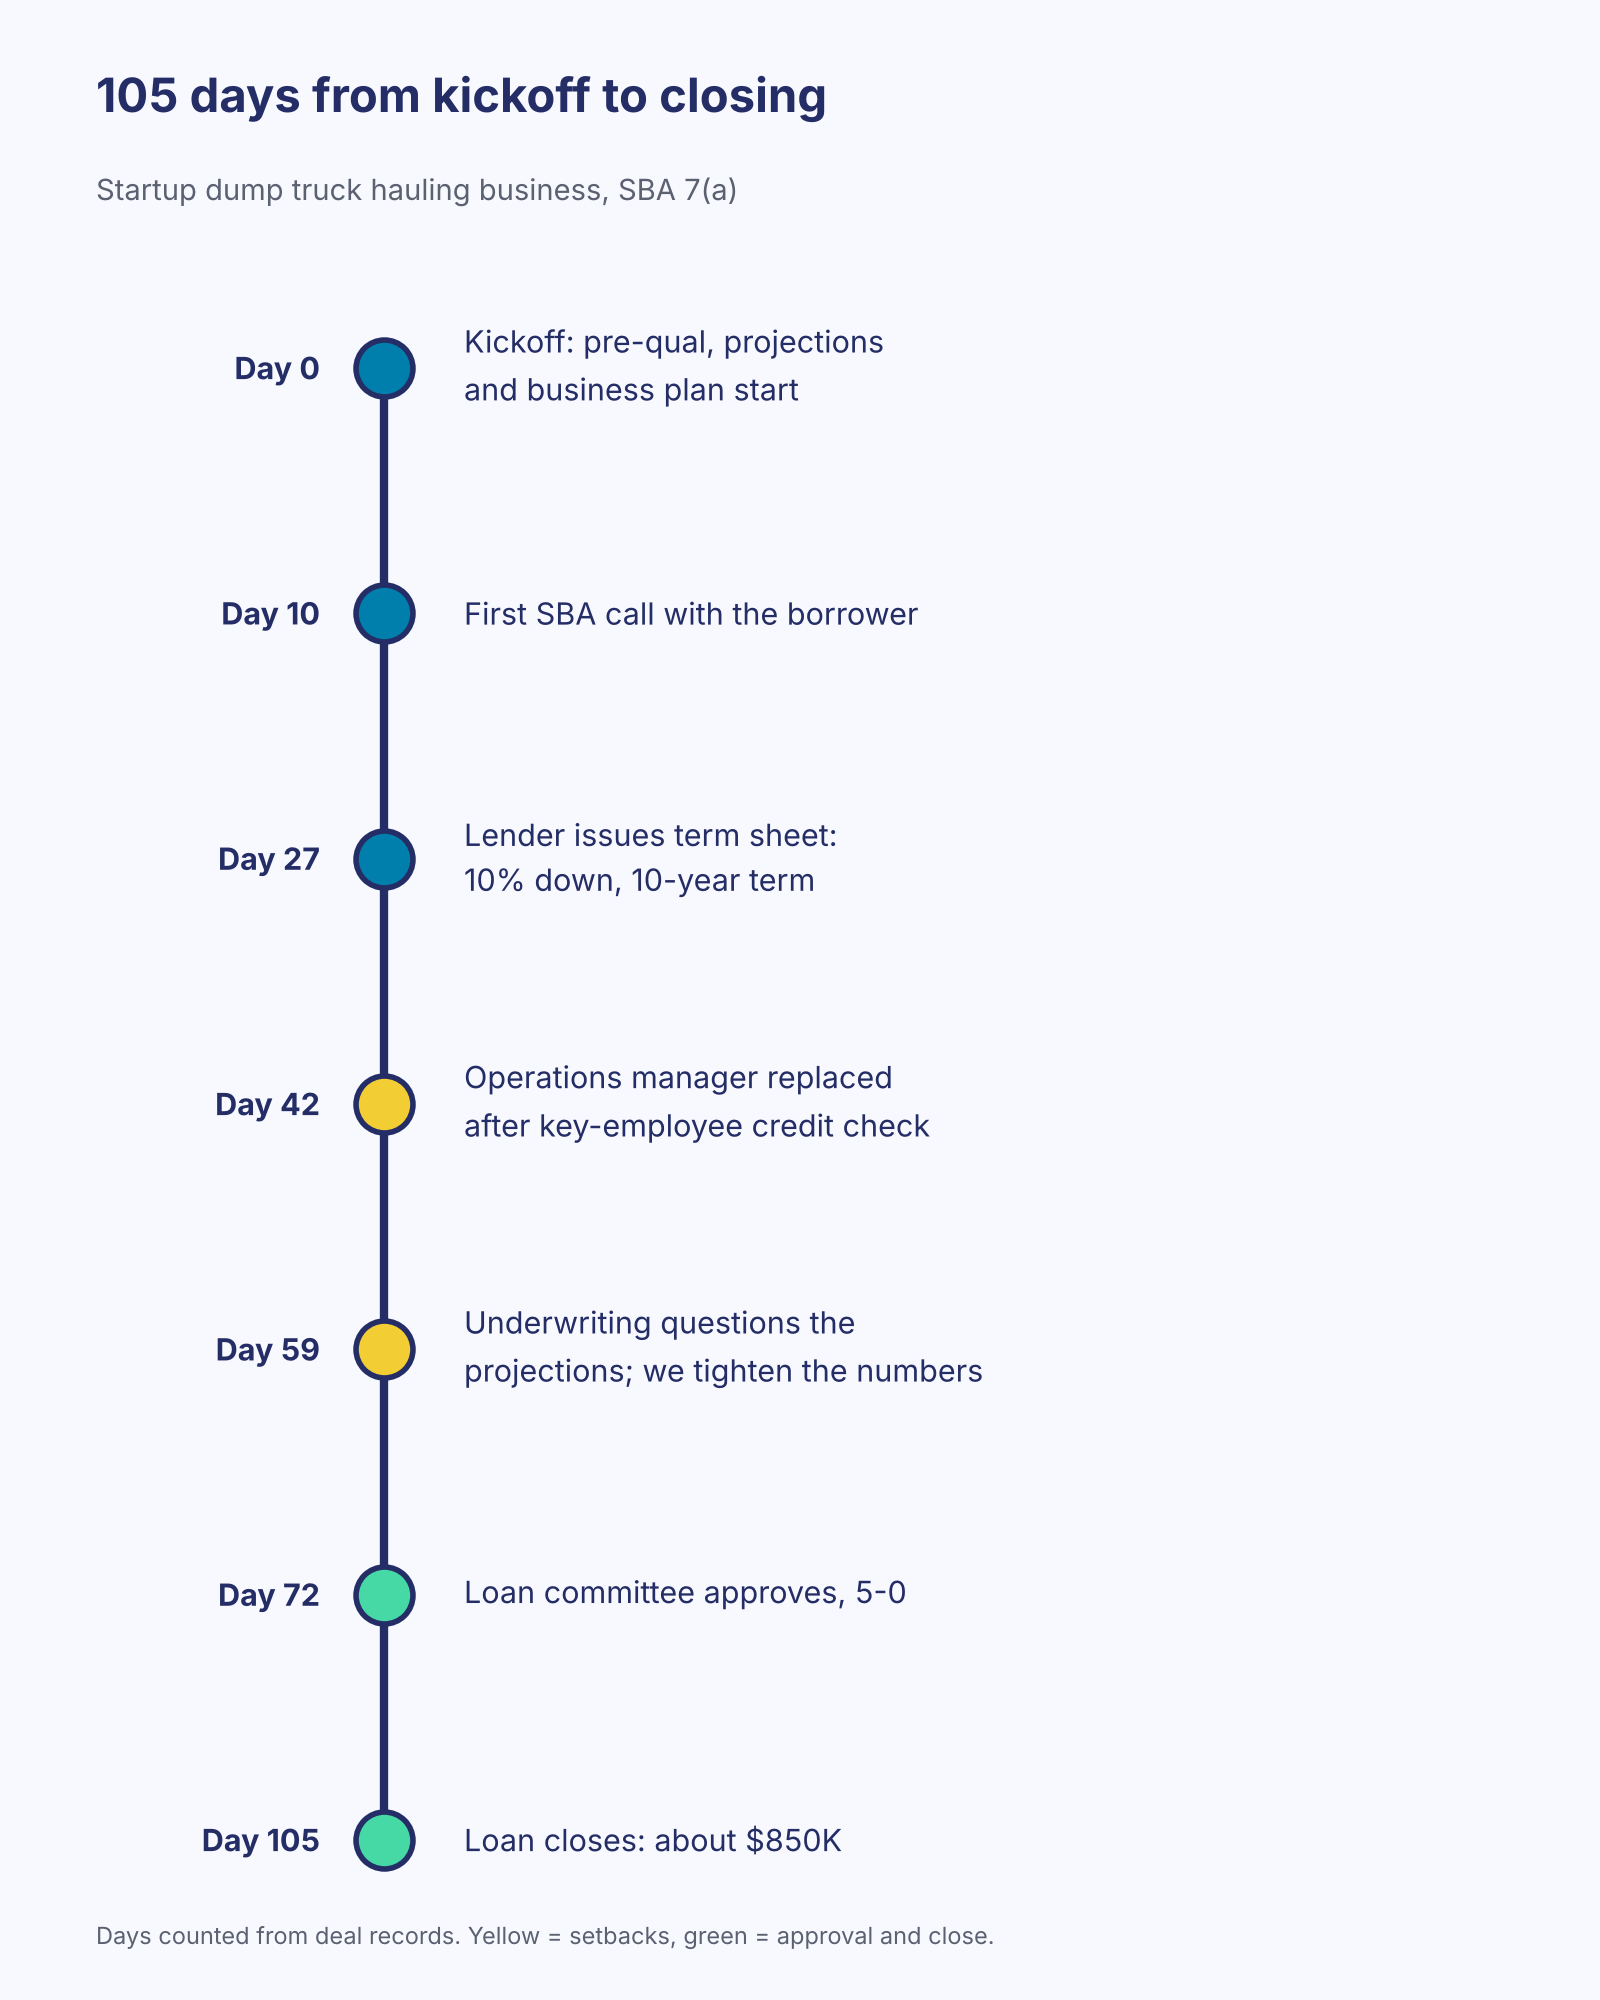
The real deal killer showed up a few weeks in. Because he wasn't a driver himself, and might stay in another state for a while before moving to where the business would run, the lender was relying on the operations manager to be there day to day. The original plan had a family member in that role. Since the lender treated him as a key employee, they pulled his credit, and it was rough.
Our team built the SBA pre-qualification, the financial projections and the business plan. The projections had to show why three trucks running double shifts, with six drivers, could cover the debt and a manager's salary.
When the operations manager issue came up, the fix was to bring in a different person with strong industry experience and a better credit history to run operations. The family member stayed on as a driver. We rewrote the plan around the new manager, including a two-year employment contract with a profit share so he'd think like an owner without being one. That's ultimately what got the deal done, but it set things back at least a few weeks.
Underwriting also pushed back on the projections. They wanted to know if the revenue was based on signed contracts. There's no way to get signed contracts for a hauling business before you have trucks, but a couple of potential customers wrote letters of intent. His background in government also gave him a real shot at public works contracts. The lender had to get comfortable that demand wasn't the problem. The real risk was finding and keeping good drivers and keeping the equipment working. We tightened the projections so every number matched.
I went straight to a national SBA lender that is also a CDFI, a mission lender. Having run a CDFI myself, I knew one is more likely to look at a startup than a traditional bank. I'd closed deals with this lender before. They weren't scared away by a startup or by trucking, where most lenders just say they can't do that industry. They don't have a strict credit box. They underwrite by hand and use common sense.
I did expect an approval once it got there. They put him through the wringer, and with this lender, by the time a deal goes to committee they've already covered the risks and can make a strong case. The committee approved it 5-0.
The loan closed at about $850K, on a 10-year term with 10% down. The rate stayed at Prime + 2.75%, the same as the term sheet. That's higher than the norm, but a startup dump truck business is a higher-risk loan, and it deserves a higher rate. It took 105 days from kickoff to closing. His biggest worry the whole way was speed. His potential customers were eager for him to start, and he didn't want to miss jobs while the process dragged on. A few days after closing, he wrote to thank our team for the business plan, the projections and the work pitching lenders.
Have questions about your own deal?
Want projections that hold up in underwriting? Our $750 SBA projection service builds the numbers lenders ask about.

Adam will review your deal before you talk to lenders and tell you honestly what lenders will flag. No cost.
Get a free SBA review