
A buyer kept her corporate sales job, hired a GM who knew the business, and closed on a garage floor coating business with an SBA 7(a) loan 46 days after her first call.
A buyer came to me wanting to purchase a small, profitable garage floor coating business for about $360K. She had a well-paying corporate sales job and planned to keep it, while a general manager who had worked at the business before as a crew lead ran the day-to-day. She wanted to move fast, and she wanted a good rate.
Her outside income, credit score, experience and the size of the loan all lined up, so I had a strong hunch this would be easy to get approved. I was confident enough that we started her business plan before we had a term sheet.
Then I saw the seller's year-to-date numbers, and they were running well behind the prior year.
That's concerning, but it's very common. Once sellers decide to sell, they take their foot off the gas. Here, the sellers had also been out of town for part of the winter, did only a handful of jobs in the first two months of the year, and had stopped chasing new work because they wanted to retire. When I looked back at the weather for the area, sure enough, there had been record-breaking cold for a long stretch, which naturally hurts this kind of work. The decline made sense, but I was still worried the lender wouldn't get comfortable with it.
The second hurdle was her house. She wanted to keep it off the loan, but once closing costs, the SBA guarantee fee and working capital were added in, the lender needed it as additional collateral.
We built the projections and a business plan that made the case directly: this business had a history of sales, and she was great at sales, as her day job and background showed. That was really the pitch. Once she was in the business and focused, she ought to be able to get the numbers back up.
When the lender questioned some of the seller's add-backs, I stripped out everything except the owner's pay on the tax return and health insurance. Even after paying the new GM, the deal still covered its debt payments more than 1.6 times.
Her day job never became the sticking point. The lender was comfortable with a GM who already knew the business. And the people who want their garage floors redone mostly have day jobs too, so evenings and weekends are often the best time for sales appointments anyway. Her own job was a commissioned sales role with a flexible schedule.
On the house, her real worry was being stuck in it for the full 10-year loan term. You can still sell a house you've pledged on an SBA loan. You give the lender notice, put the proceeds toward your next house, and let the lender take a second mortgage on the new one. What you can't do is sell and spend the equity on a boat. Once she understood that, she was comfortable pledging it.
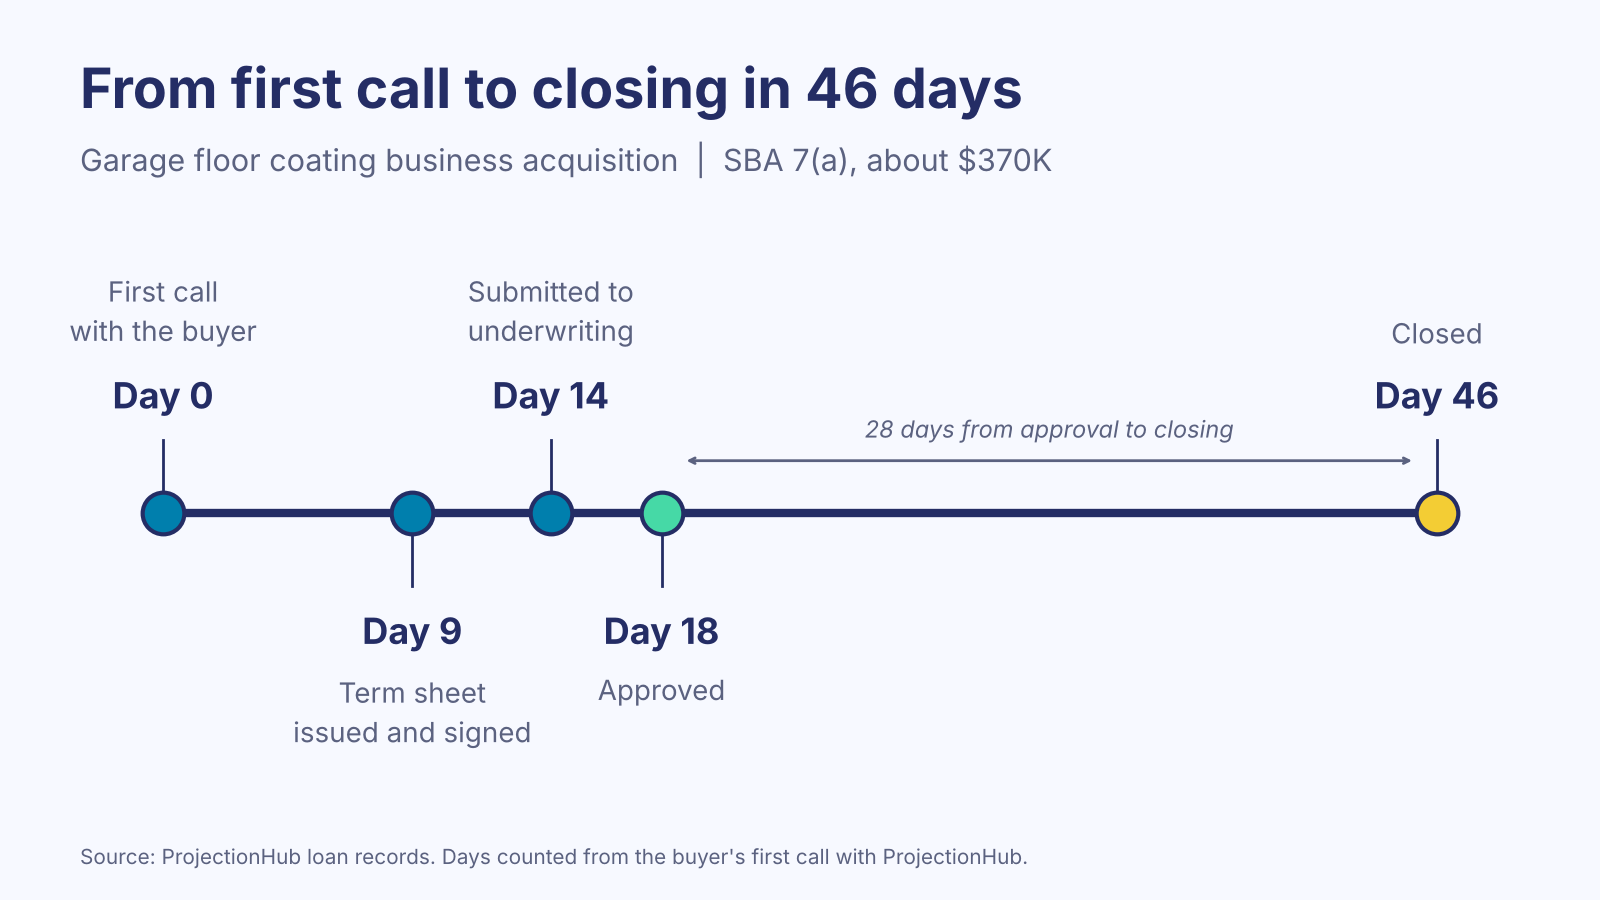
A national SBA lender showed early interest, and a community bank I'd closed deals with before sent a term sheet nine days after our first call.
In my experience, the really fast lenders tend to be priced a little higher, and the lowest-rate lenders tend to be slow. She wanted both. I told her we could keep shopping, but that would restart the clock and probably mean about 60 days to close, while this lender could likely close within about three weeks of a commitment letter.
So I went back to the lender and asked them to sharpen their pricing to win the deal. They agreed and came in 0.75% under their usual pricing, at Prime + 2%. It isn't the lowest rate out there; my guess is it's close to average or a bit below for this size. Small loans leave lenders little room, because closing a $350,000 loan takes about as much work as closing a million-dollar one.
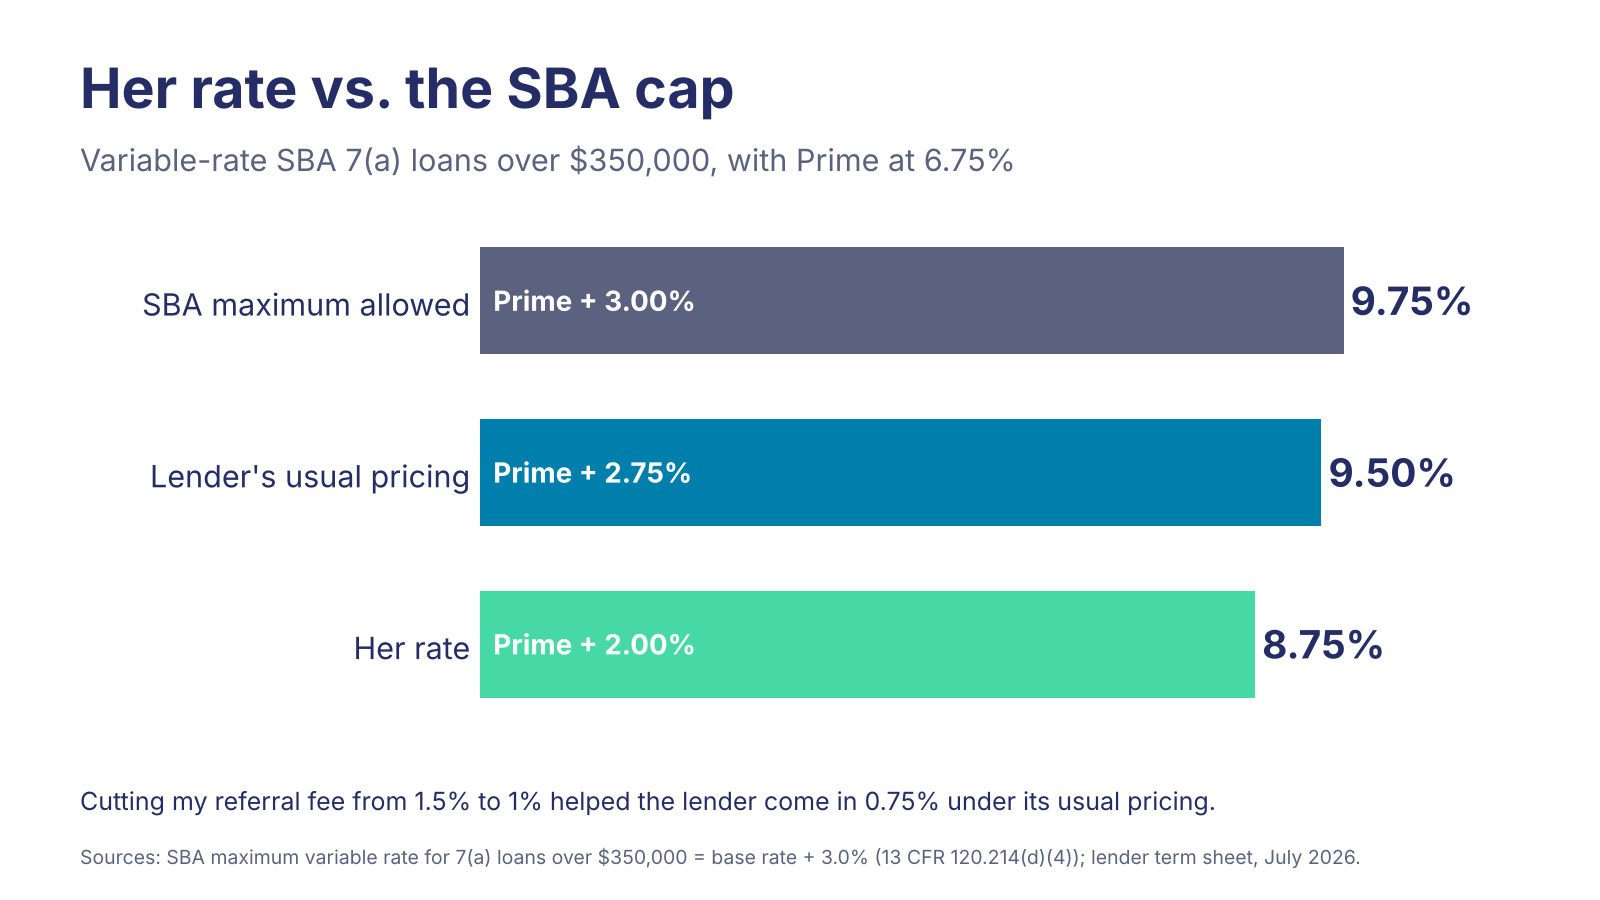
She signed the term sheet the evening it arrived. The loan was approved on day 18 and closed on day 46: about $370K, 10 years at Prime + 2% variable, no prepayment penalty, about 10% down, with working capital built into the loan since the lender doesn't offer lines of credit. She asked for two weeks' notice before closing so her GM could leave his job and they could take over the projects the sellers already had scheduled.
What stuck with me was how organized and fast she was. She answered every question quickly and in detail, and she always did what she said she would. If she treats customers the way she treated this process, I knew she was going to do really well.
Have questions about your own deal?
If you're looking at buying a business and wondering whether the numbers will work, reach out to me directly at adam@projectionhub.com.

Adam will review your deal before you talk to lenders and tell you honestly what lenders will flag. No cost.
Get a free SBA review